

UiPath’s 24% return over the past six months has outpaced the S&P 500 by 15.1%, and its stock price has climbed to $13.37 per share. This run-up might have investors contemplating their next move.
Is there a buying opportunity in UiPath, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is UiPath Not Exciting?
We’re glad investors have benefited from the price increase, but we’re passing on UiPath for now. Here are three reasons why PATH doesn’t excite us, plus one stock we’d rather own.
1. Weak ARR Points to Soft Demand
While reported revenue for a software company can include low-margin items like implementation fees, annual recurring revenue (ARR) is a sum of the next 12 months of contracted revenue purely from software subscriptions, or the high-margin, predictable revenue streams that make SaaS businesses so valuable.
UiPath’s ARR came in at $1.94 billion in Q2, and over the last four quarters, its year-on-year growth averaged 11.7%. This performance was underwhelming and suggests that increasing competition is causing challenges in securing longer-term commitments. 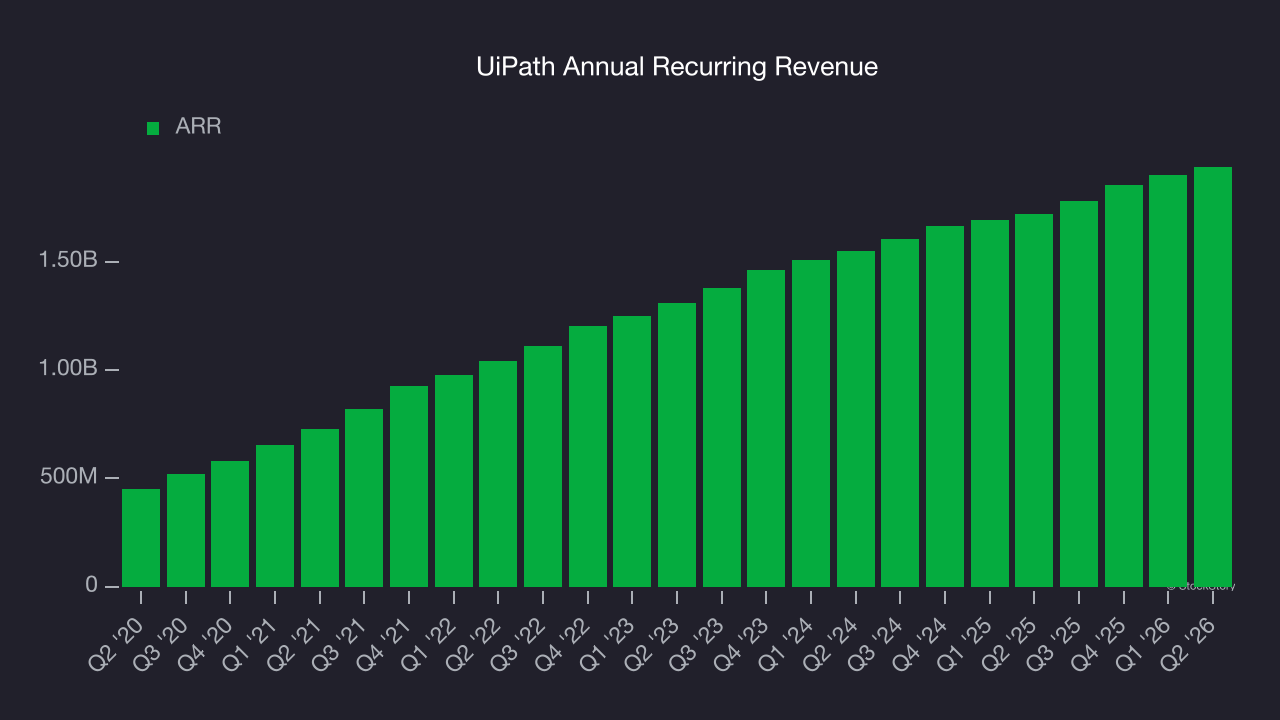
2. Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect UiPath’s revenue to rise by 8.2%, a deceleration versus its 18.5% annualized growth for the past five years. This projection doesn’t excite us and suggests its products and services will face some demand challenges.
3. Long Payback Periods Delay Returns
The customer acquisition cost (CAC) payback period represents the months required to recover the cost of acquiring a new customer. Essentially, it’s the break-even point for sales and marketing investments. A shorter CAC payback period is ideal, as it implies better returns on investment and business scalability.
UiPath’s recent customer acquisition efforts haven’t yielded returns as its CAC payback period was negative this quarter, meaning its incremental sales and marketing investments outpaced its revenue. The company’s inefficiency indicates it operates in a highly competitive environment where there is little differentiation between UiPath’s products and its peers.
Final Judgment
UiPath isn’t a terrible business, but it doesn’t pass our quality test. With its shares beating the market recently, the stock trades at 3.7× forward price-to-sales (or $13.37 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re pretty confident there are more exciting stocks to buy at the moment. Let us point you toward one of Charlie Munger’s all-time favorite businesses.
Stocks We Would Buy Instead of UiPath
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.